Chinese GPU companies are looking for a market beyond the data centre, and robots are one answer. Shanghai-based Anxin Technology recently added Zhuhai Biren Integrated Circuit as a shareholder. Separately, UBTech disclosed that Xixuan Chuangzhi, a venture it launched with MetaX, closed a RMB 500 million angel round for a first product aimed at robot-side computing.
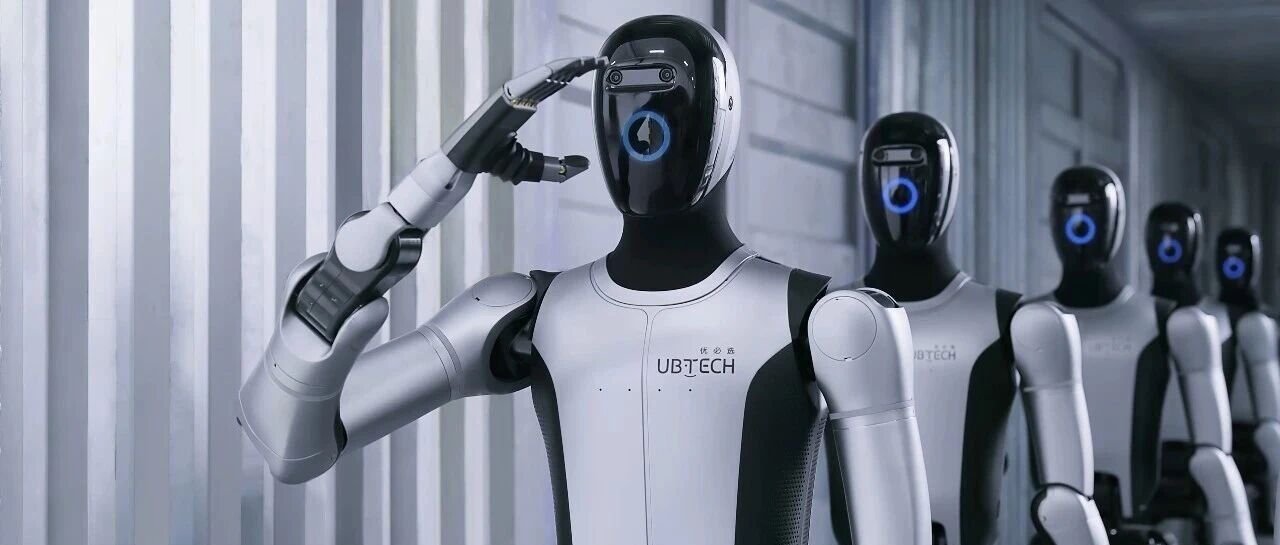
Anxin, incorporated in December 2025, focuses on physical AI and plans to combine its own NPU architecture with on-device inference models and precision motion control. Biren now holds about 2.81 per cent. Other shareholders include funds affiliated with Hillhouse and iFlytek Ventures. The controller, Sun Erjun, previously helped found MetaX, which listed on the STAR Market in December 2025.
Five months later his former employer entered the same race. Xixuan Chuangzhi is positioning its first chip as a brain-and-cerebellum system-on-chip for robots, benchmarked against Nvidia’s Thor, with a development platform in 2027 and volume production in 2028. The angel round will fund chip development, toolchains and joint validation with customers. Moore Threads and Iluvatar CoreX, two other members of China’s GPU quartet, have already shipped robot-side modules. Nvidia has stitched the whole pipeline together: Cosmos for synthetic training data, Isaac Sim and Isaac Lab for simulation, data-centre GPUs for training, Jetson for on-robot deployment and TensorRT for inference.
Why build when you can buy
IDC raised its 2030 forecast for global humanoid shipments by about 50 per cent in September, to more than 750,000 units. In the first half of 2026, nearly 25,000 humanoids shipped worldwide, up 432.1 per cent year on year. That gives GPU vendors a reason to sell compute modules into the machines themselves. But more chips do not guarantee a fit, and robotics companies now choose between buying off the shelf, co-developing with a supplier and founding a joint venture.
Cost is one driver. UBTech’s Zhou Jian has said overseas chips are too expensive, taking a third of hardware bill of materials. Switching to domestic parts carries its own adaptation cost in engineering time. Galbot signed a deal in November 2025 with automotive-grade chip maker SemiDrive to co-develop a next-generation robot chip, contributing multimodal model and real-world requirements while SemiDrive supplies development and supply-chain experience.
Building earlier gives a company more room to adjust before a design freezes. Noetix and GigaDevice worked together from the initial chip selection of the consumer humanoid Bumi through to mass production. For the next generation, Noetix wants 21 degrees of freedom in a compact body and is evaluating a new joint-control chip from GigaDevice that integrates part of the circuitry needed to read motor position and speed, reducing components on the drive board. Knowing early how small a board can be gives the mechanical team more freedom.
The amortisation question
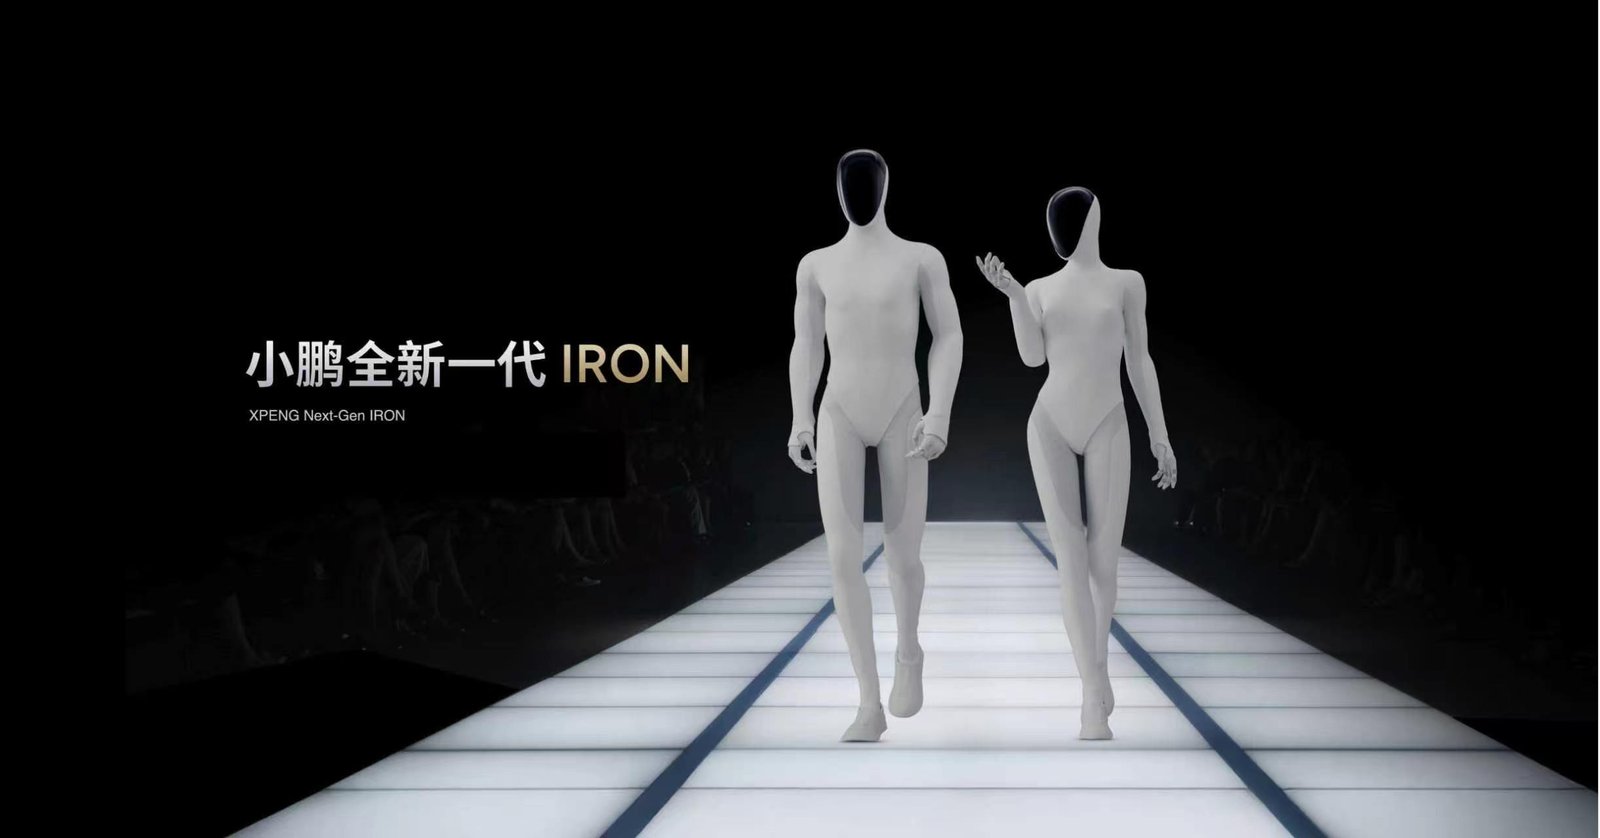
Companies selling both cars and robots can spread chip development across two product lines. XPeng’s IRON humanoid uses the same Turing chip as its vehicles, with more than 200,000 units shipped, almost all from cars. Its research spend is carried mainly by the auto business, and unit manufacturing cost has dropped to RMB 2,500 to RMB 3,000. For a company whose only volume is robots, making a chip that fits the machine is an engineering problem that sustained investment can solve. The harder question is whether in-house is cheaper than buying. Only continuous orders and growing deliveries spread development across enough units to make that true, which turns a chip decision into a test of commercialisation.
Editor’s note: This is an adapted translation of the original 36Kr report. It has been trimmed and restructured for readability for an international business audience. The full original (in Chinese) is at https://m.36kr.com/p/4074892228335236.