1. The Ranking
2. Three Signals
Signal 1
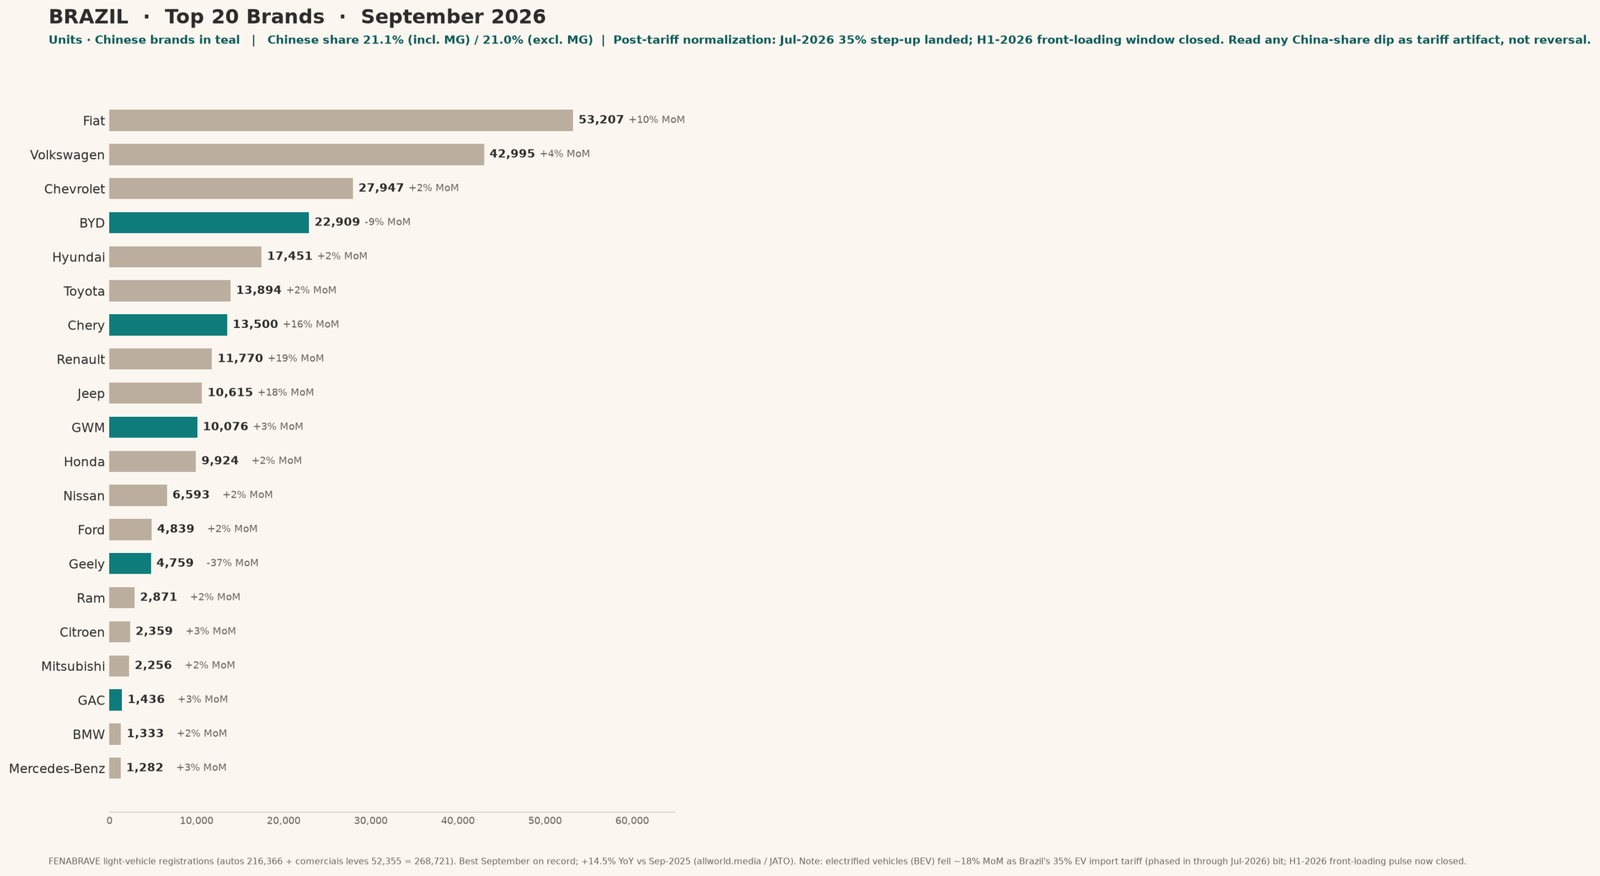
- Fact: BYD held 4th place in Brazil for a fourth straight month with 22,209 units (about 8.3% share), but it slipped 9% month on month from its August record as the surging Fiat opened a wider lead.
- Read: A Chinese brand inside the historical Big Three is still the new normal, but the post-tariff cool-down has started. BYD’s dip is a mix story (direct-sales ramp, EX2 tariff hit), not a collapse.
Signal 2
- Fact: Chinese brands took about 21.1% of Brazil’s light-vehicle market in September 2026 (21.0% excluding MG), down from 22.8% in August and 22.7% in July.
- Read: One in five cars still wears a Chinese badge, but the climb flat-lined the month the H1 front-loading window closed. Read the dip as tariff normalization, not a reversal. The bloc’s ex-MG share barely moved.
Signal 3
- Fact: GWM and the Chery group (Caoa Chery plus Omoda Jaecoo) both set records in September at roughly 10,100 and 14,400 units, while Geely fell about 37% to 4,759 as its imported EX2 hatch hit the 35% wall ahead of local EX5 production.
- Read: The China bloc is splitting along the tariff line. Brands with local assembly (BYD Camaçari, GWM Iracemápolis, Caoa/Chery) hold or grow; pure importers like Geely’s EX2 take the hit. The September shape tells you who has a plant.
3. The Take
Brazil just posted its best September on record, 268,721 light vehicles, up about 14% year on year, and the China bloc spent the month proving the tariff wall did not break it. BYD held 4th for a fourth straight month with 22,209 units, but that was down 9% from its August record as Fiat surged to 19.8% share and opened the biggest lead of the year. Chinese brands took about 21.1% of the market, down from 22.8% in August and 22.7% in July.
That dip needs a clear reading. Brazil’s EV import tariff (BEV, PHEV and HEV) climbed to its full 35% rate in July 2026, and the first half of the year showed the classic front-loading pulse, with brands pulling volume forward to beat the wall. September is the third full month after that step-up, and the battery-electric segment fell roughly 18% month on month. So the share line softened for a reason that has nothing to do with demand. Read the dip as tariff normalization, not a reversal.
The structural point is who held up. GWM took 9th with a record 10,076 units, and the Chery group (Caoa Chery plus Omoda Jaecoo) set its own record at roughly 14,400, five Chinese names now inside Brazil’s top fifteen. Geely is the cautionary case. It fell about 37% to 4,759 as its imported EX2 hatch ran straight into the 35% wall, months before local EX5 production comes on line. The bloc is splitting along the plant line, and September shows exactly which names have one.
The question for the incumbents is whether 21% is the ceiling or the floor. The tariff is up, local assembly is absorbing the hit, and the China bloc still owns a fifth of Latin America’s largest market. The next months tell you which, but the direction is no longer in much doubt.
4. Sources
- Source: FENABRAVE monthly report (autos + comerciais leves).
- Published: 2026-10-02.
- Cross-checked: Bright Consulting consensus (guiadocarro, vrum, autoforum/Quatro Rodas); allworld.media and Fenabrave official release; cafecominformacao (BYD direct/retail split); webmotors/JATO retail ranking; EVBytes/CleanTechnica dealer-report field notes..
- Basis: FENABRAVE light-vehicle registrations (autos 216,366 + comerciais leves 52,355 = 268,721). Best September on record; +14.5% YoY vs Sep-2025 (allworld.media / JATO). Note: electrified vehicles (BEV) fell ~18% MoM as Brazil’s 35% EV import tariff (phased in through Jul-2026) bit; H1-2026 front-loading pulse now closed.
- FENABRAVE monthly report, released 2026-10-02 (light vehicles, autos + comerciais leves). allworld.media: autos 216,366 (+21.2% YoY); LCV 52,355 (-0.9% YoY); combined 268,721, best September on record.
- Cross-check: vrum (Bright Consulting) — Fiat 19.8% share, Volkswagen 16.0%, Chevrolet 10.4%, BYD 8.2% (down from 9.4% in August); Geely -1.1pp, Chery +0.6pp, Renault +0.6pp, Jeep +0.5pp.
- Cross-check: cafecominformacao — BYD total 22,209 (14,946 retail + 7,263 direct sales), 4th place, 8.5% market share; Dolphin Mini 9,385 units (first EV in Brazil’s all-time top 3).
- Cross-check: guiadocarro (Bright Consulting, first half of Sept) — Fiat 20,573, VW 16,938, BYD 10,230, Chevrolet 9,273, Hyundai 8,318, Toyota 6,305; first-half light-vehicle total 109,536.
- Cross-check: webmotors/JATO retail ranking (Sept) — Dolphin Mini led retail (5,886); Caoa Chery Tiggo 7 4,015; Omoda 5 3,615; BYD Dolphin 3,008; Geely EX2 2,118; Geely EX5 1,873.
- Tariff policy: Brazil’s EV import tariff (BEV/PHEV/HEV) reached its full 35% rate in July 2026 (phased from 2024). H1-2026 showed a front-loading pulse ahead of the step-up; September 2026 is the third full month after the wall. The BEV segment fell ~18% MoM (FENABRAVE), so the dip in Chinese-brand share this month is a tariff-normalization artifact, NOT a structural reversal. BYD (Camaçari), GWM (Iracemápolis) and Caoa/Chery (local assembly) absorbed the wall; Geely’s imported EX2 hatch took the hit ahead of local EX5 production (started Sept-2026).