What was a marketing asset became a liability
After the Mid-Autumn holiday the humanoid robotics industry in China met something more consequential than another round of online argument. The data-collection dispute that had been building for weeks turned into hard remedial rules from regulators and the capital markets.
IPO window guidance for humanoid robot companies has formally landed, according to Wallstreetcn Tech Insight. Listing reviews for the sector have tightened noticeably, several companies in the queue have had their progress suspended, and investment banks have raised their risk-control standards across the board.
In a few months the public mood, the logic of primary-market funding and the bar for an IPO have all been rewritten at the same time. Data collection, until recently treated as core industrial infrastructure, is now the sensitive zone of the sector. Leading companies have started to distance themselves quietly, and an avoidance etiquette has formed inside the industry: do not discuss data collection, do not touch it.
The honest description of the current state is that no company has publicly admitted to improper practice, yet almost every player in the sector is running an internal audit, pulling promotional content and freezing new government and enterprise data-collection projects.
A year ago the logic was the opposite. Building large-scale data-collection bases and accumulating huge scene datasets was how a robotics company proved its research capability, lifted its valuation and pushed towards funding and an IPO.
Core infrastructure that changed character
What decides the long-term technical ceiling and core competitiveness of a company is not the surface demonstration but high-quality, scene-specific, reusable real industrial data, one frontline venture capitalist told Wallstreetcn Tech Insight on condition of anonymity. Outsiders looking at an embodied-AI company tend to see only the impressive demo.
Data quality and scene coverage directly determine how well a robot model generalises and how reliably it deploys. They are the base layer under machine iteration and commercial rollout. In earlier years the competition was straightforward. Whoever held more data across more scenes held the technical advantage. Nobody expected this core infrastructure to turn into a risk label that the whole industry avoids.
Companies are drawing boundaries in different ways. Beijing-based Songyan Power chose to cut clean. Founder Jiang Zheyuan has stated publicly that the company took no data-collection centre orders at all this year and that all of its revenue comes from genuine market-facing scenes such as business-to-business services and consumer robots.
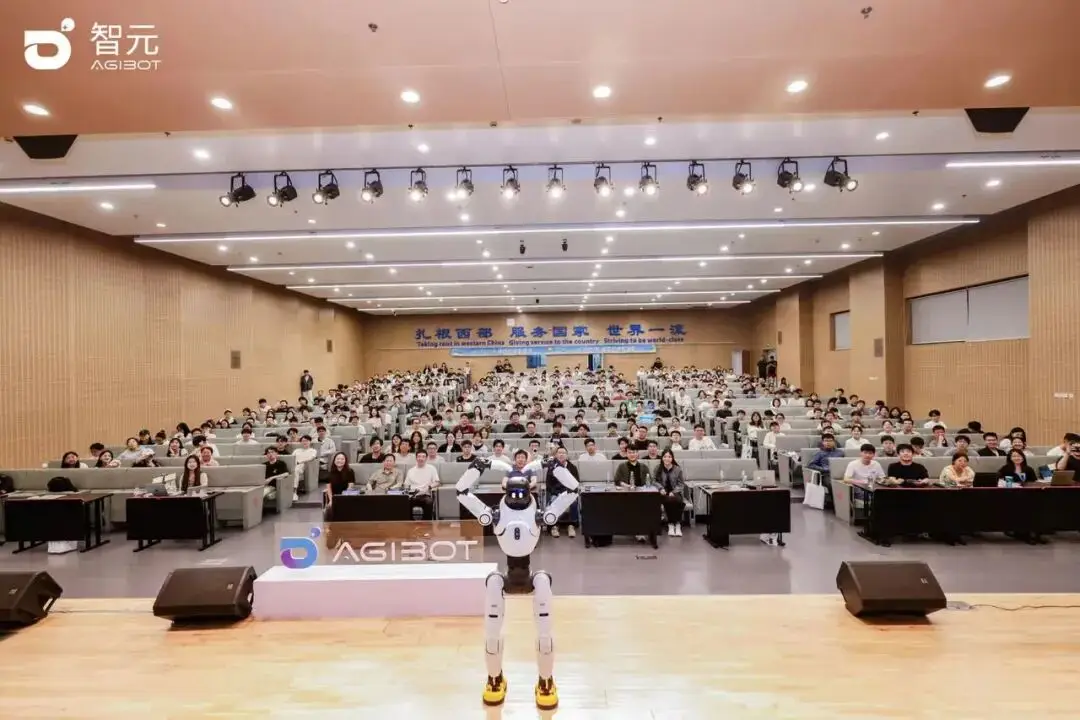
Agibot represents the other mainstream response. During the data-collection boom Agibot built a platform through its Mifeng Technology unit, stressing self-developed, self-used and technology-enabled operations with data feeding back into model iteration, and aiming for data capacity in the tens of millions of hours. After the dispute flared, Agibot stayed quiet. It neither cut public ties nor took sides. The market broadly reads its data-collection spending as serving real technical iteration, a necessary research investment rather than idle arbitrage, and treats it as a sample of the compliant model.
These two very different responses send the same message to the capital markets. How a data-collection business is transacted and why it exists has become a yardstick for judging the real quality of a company’s operations.
The unspoken rule that broke into the open
The flight from the sector traces back to a hidden grey practice being exposed in public. In September 2026 Shao Tianlan, founder of Mekamind, spoke out and described how data-collection accounting was being manipulated in the robotics sector. That intervention pushed regulators to tighten and investors to revalue, making it the most important trust turning point for Chinese robotics this year.
Mekamind listed on the Hong Kong exchange on 1 September. Nine days later Shao began posting repeatedly, aiming at a group of companies he described as assembling deals rather than building products, using local government and enterprise data-collection centres, related-party leasing and closed-loop transactions to dress up fake revenue. He called this kind of operation illegal, immoral and unwise, saying it burns the reputation of the sector and damages investors in the capital markets.
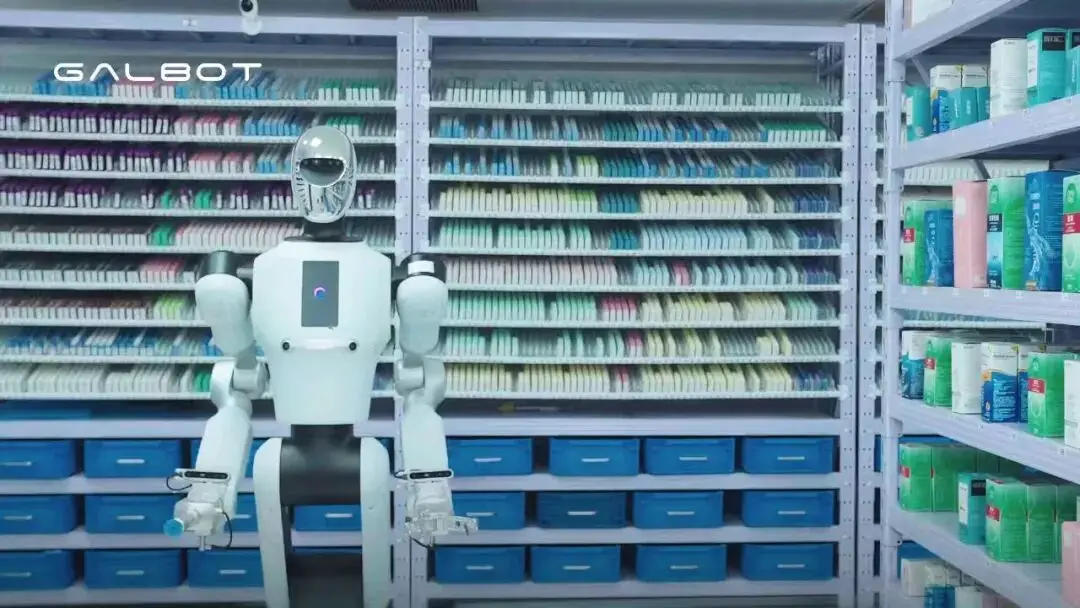
He named Galbot directly as the type case, saying it used local state-owned data-collection projects to close the loop on its books, leaned on policy funding to inflate its nominal scale, and used fabricated flows to push up its valuation and sprint towards an IPO. That punctured an arbitrage game the industry had long kept unspoken.
The response from Galbot went through two stages. Its first statement stressed only that it was focused on deploying technology and was unbothered by short-term noise, sidestepping the central questions about idle data collection and related-party transactions. As the pressure grew the company issued a formal statement denying fabricated revenue, describing the claims as malicious rumour and announcing a police report. Neither response answered the questions of the market point by point, and neither settled them.
Shao also drew the line on what is compliant. Government and enterprise procurement with real delivery, continuing deployment and genuine scene value is normal industrial activity. What he classified as bubble arbitrage is a closed-loop data-collection transaction with no real customer, no deployed scene and no purpose except to flatter the accounts using fiscal transfers.
That public confrontation laid the grey zone of the sector in front of capital and regulators and pushed both the primary and secondary markets to tighten their reviews at the same time. After Shao spoke, several media outlets followed with on-the-ground reporting that confirmed the practice is widespread. Many government and enterprise data-collection centres across the country are sustained by fiscal transfers, with the core purpose of making the revenue of a company look bigger and its valuation more attractive. These projects commonly share three absences: no genuine outside customer, no continuing commercial demand and no industrial deployment value.
Market perception has now reversed. Data collection is no longer industrial infrastructure. It has become a synonym for related-party transactions and inflated reporting. Investment banks and primary-market institutions have settled on a blunt consensus. The companies named may be isolated cases, but the scrutiny covers the whole sector. Any company caught in a closed-loop government or enterprise data-collection project goes onto the enhanced review list.
Funding and listing locked down together
As the dispute ran on, the window guidance landed after the Mid-Autumn holiday and the sector reached a genuine turning point. Primary-market funding and IPO review tightened in step.
Sector capital had been running hot. Domestic embodied-intelligence funding reached RMB 93.5 billion in the first half of 2026, five times the level of a year earlier. A large group of companies whose valuations rested on data-collection flows rushed towards listings in Hong Kong and on the A-share market, and in the first half alone 26 robotics companies listed or queued on the Hong Kong exchange.
With the window guidance in place, the listing bar has risen sharply. Regulators have set new standards for embodied-intelligence IPOs: strict verification of revenue authenticity, business sustainability and self-developed core technology, with particular attention to government-enterprise related revenue, closed-loop data-collection transactions and non-market flows. Companies that depend on policy transfers, lack market-based deployment and have no repeat customers are being suspended or quietly discouraged. Many that had already filed have received requests for supplementary compliance checks, and their listing progress has stalled. Secondary-market enquiry standards have risen too. From the second quarter of 2026, revenue authenticity, the reasonableness of related-party transactions and margin sustainability have become fixed lines of questioning for robotics companies appearing before the Shanghai STAR Market and the Beijing Stock Exchange. The route to listing on polished numbers is largely closed.
Primary-market investment logic has been rebuilt as well. A private equity source told Wallstreetcn Tech Insight that institutions have updated their due-diligence frameworks to look through to order sources and delivery authenticity, and are stripping out the valuation attributed to inflated data-collection revenue. Several leading institutions have paused new project approvals in order to prioritise compliance risk in existing portfolios. Financing channels for arbitrage-style companies are effectively shut, and capital is concentrating faster on companies with real mass production, market-based repeat purchases and hard self-developed capability.
Why the arbitrage appeared at all
The underlying cause is a serious mismatch between how fast the industry can deploy and how fast capital wants it to grow.
Humanoid robots are still at an early research stage. Hardware maturity is limited, debugging is expensive and the commercial price-performance case is weak. AI models generalise poorly, struggle to adapt to complex real scenes, and much of the research data cannot be converted into commercial orders. Genuine market-based bulk purchasing demand is scarce.
Meanwhile the interests of companies, local governments and capital have become tightly bound. Companies need presentable financials to support funding and an IPO, local governments need high-tech industrial results, and capital needs a high-growth story for its portfolios. With real market orders absent, closed-loop government and enterprise data-collection transactions became the shortcut to fast revenue growth and the appearance of a booming industry. Delayed deployment produced the arbitrage, and policy-driven fake transactions filled the gap left by genuine commercial demand.
Regulatory and public pressure together have ended the crude, high-profile model of data-collection padding. They have not removed the incentive to flatter the accounts and defend a valuation. The contest of interests has simply moved from open promotion to quieter, more finely engineered operations. Large closed-loop data-collection orders and idle data-collection sites are the easiest to dismantle and the easiest for regulators to see through, and they are being retired. One risk-control specialist said the next generation of techniques will be more embedded and harder to isolate.
A single large data-collection order is easy to identify, so companies are folding data collection, model tuning and scene iteration into maintenance service contracts, project subcontracting and technical consulting agreements, blurring the line between research spending and reporting cosmetics. Overt arbitrage is gone. The grey contest continues, which is the normal shape of a bubble deflating in a hard-technology sector.
Sector assets are polarising further. Data-collection heavy assets built purely on policy support and carrying little research value are falling idle or going unfinished, sunk costs left behind by the bubble. The data collection that genuinely serves technical iteration is returning to its research role, no longer chasing scale for its own sake or trading on a concept.
The reshuffle is not over. Companies that stick to market-based deployment keep absorbing industrial resources and setting the terms. Arbitrage-driven companies will not all be cleared out at once, but their funding, valuations and listing channels stay constrained, and their room to operate keeps shrinking.
Editor’s note: This is an adapted translation of the original OFweek Robotics report. It has been trimmed and restructured for readability for an international business audience.