1. The Ranking
2. Three Signals
Signal 1
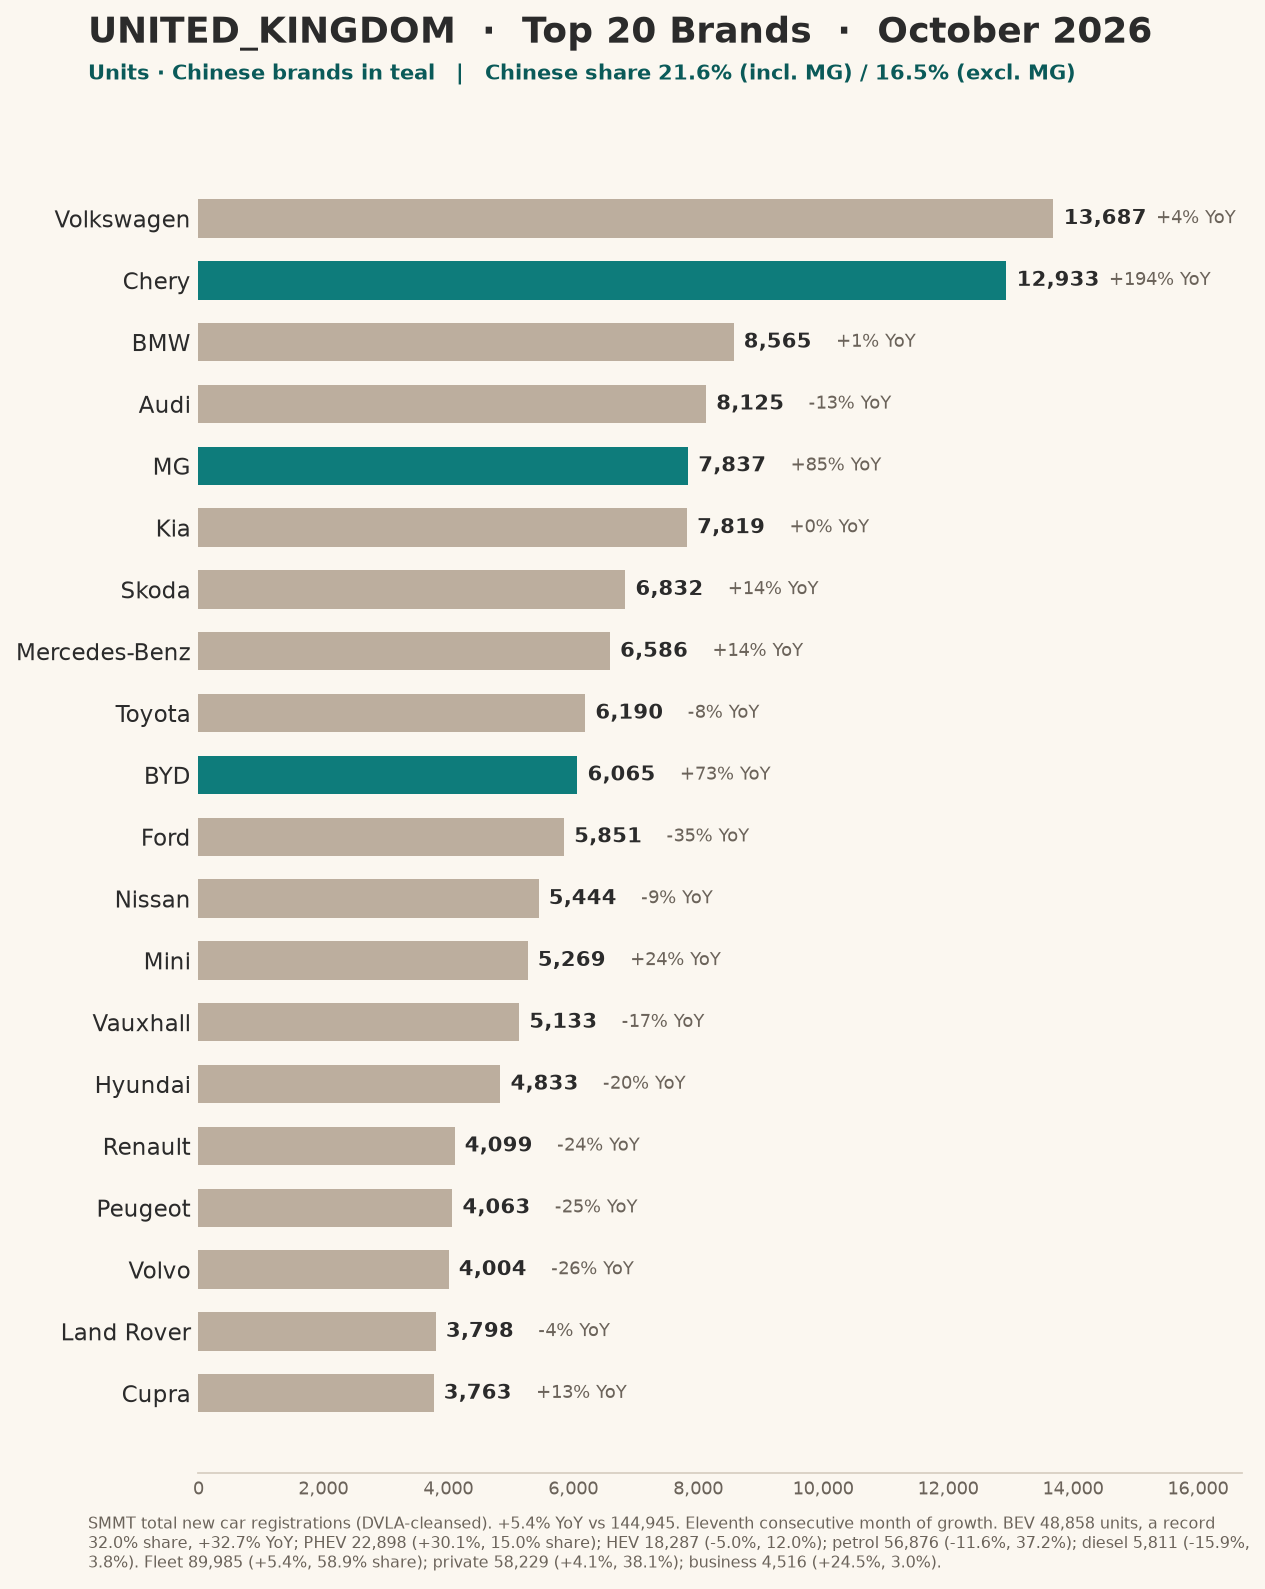
- Fact: Chinese brands took 21.6% of UK registrations in October 2026 (16.5% without MG), down from the 23.3% record set in September’s plate-change month but still the second-highest share on record.
- Read: Strip out the September 76-plate spike and the underlying run-rate is a Chinese share in the low twenties, not a one-month flash. The ex-MG line is 16.5% and climbing, so the old ‘it is only MG’ caveat no longer holds.
Signal 2
- Fact: The Chery group (Chery, Jaecoo, Omoda and Lepas) combined for 13,589 units, just 98 behind Volkswagen’s 13,687, after outselling VW in September.
- Read: The ‘China’s biggest carmaker’ headline was a September plate-change artifact. A month later the same four badges sit within 100 units of VW and ahead of every other legacy marque. The grouping still out-sells BMW and Audi individually, it just no longer tops the table.
Signal 3
- Fact: MG was the leading Chinese brand at 7,837 units (No.4 overall, +85.1% year on year), while the Jaecoo 7 was Britain’s best-selling car for a second straight month at 3,412 and two more Chinese nameplates (MG HS, Jaecoo 5) sat in the top ten.
- Read: Three Chinese models in the national top ten is no longer a September effect. MG’s growth plus Chery’s sub-badge spread anchors the Chinese presence in the upper third of the chart, and Tesla’s 282 units (its quiet first month of the delivery quarter) shows who is capturing the electric growth.
3. The Take
Britain’s car market posted its eleventh straight month of growth in October, 152,730 registrations, up 5.4% year on year, and the China bloc took 21.6% of it (16.5% without MG). That is down from the 23.3% record set in September, but September was a plate-change month. Strip that out and the underlying run-rate is a Chinese share in the low twenties, which a year ago would have been unthinkable.
The most telling shift was at the top of the carmaker table. In September the Chery group (Chery, Jaecoo, Omoda and the new Lepas badge) combined for 32,830 units and outsold Volkswagen. In October the same four badges totalled 13,589, just 98 behind VW’s 13,687. The ‘China’s biggest carmaker’ headline was a one-month plate-change artifact. A month later the group still out-sells BMW and Audi individually and sits a whisker off the largest legacy name, so the story did not disappear, it just stopped being a clean win.
MG stayed the leading Chinese brand at 7,837 units, No.4 in the country and up 85.1% year on year, while the Jaecoo 7 became Britain’s best-selling car for a second straight month at 3,412, ahead of the Ford Puma. Two more Chinese nameplates, the MG HS and the Jaecoo 5, sat inside the top ten, so three of the ten best-selling cars in Britain now wear a Chinese badge. Against that, Tesla registered 282 cars, down 44.8%, its quiet first month of the delivery quarter after September’s 15,875 push. The electric growth is being captured by everyone except Tesla.
Watch the tariff gap, not the monthly wobble. Britain still charges Chinese-built cars the standard 10% duty and has not followed the EU’s anti-subsidy tariffs, which is exactly why the China bloc is growing faster here than on the continent. October’s dip from the September record is a plate-cycle effect, not a reversal. The question for 2027 is whether London closes the gap that Brussels opened, because the curve above was built on it.
4. Sources
- Source: SMMT new car registrations.
- Published: 2026-11-05.
- MG counted as SAIC (Chinese). Chinese share shown with and without MG.
- Cross-checked: SMMT ‘By Brand’ October 2026 marque table (final figures published Mon 5 Nov 2026; preliminary issued 4 Nov). Total new car registrations 152,730, +5.4% YoY vs 144,945; eleventh consecutive month of growth and the strongest October since 2019. Chinese-badged marques total 32,972 units = 21.6% of the market (brand_map incl. MG; Lepas counted as Chery). Chery group (Chery 3,707 + Jaecoo 6,089 + Omoda 3,137 + Lepas 656) = 13,589, behind Volkswagen (13,687) by under 100 units for the month. BYD 6,065 was the No.4 brand overall; MG 7,837; Jaecoo 6,089. Cross-check: Autocar reported combined Chinese share 21.3% incl MG (record 23.3% in Sept); teslant.com confirmed BEV 48,858 (32.0% share, +32.7%) and Tesla 282 (first month of delivery quarter). Note: SMMT headline total 152,730 reconciles exactly with the by-brand table sum..
- Basis: SMMT total new car registrations (DVLA-cleansed). +5.4% YoY vs 144,945. Eleventh consecutive month of growth. BEV 48,858 units, a record 32.0% share, +32.7% YoY; PHEV 22,898 (+30.1%, 15.0% share); HEV 18,287 (-5.0%, 12.0%); petrol 56,876 (-11.6%, 37.2%); diesel 5,811 (-15.9%, 3.8%). Fleet 89,985 (+5.4%, 58.9% share); private 58,229 (+4.1%, 38.1%); business 4,516 (+24.5%, 3.0%).
- SMMT marque table ‘By Brand’ October 2026 (Cars_10_2026.xlsx, final figures published Mon 5 Nov 2026, 9am). Total 152,730, +5.4% YoY vs 144,945. Eleventh consecutive month of growth.
- SMMT powertrain table: BEV 48,858 (32.0% share, +32.7%); PHEV 22,898 (15.0%, +30.1%); HEV 18,287 (12.0%, -5.0%); petrol 56,876 (37.2%, -11.6%); diesel 5,811 (3.8%, -15.9%).
- SMMT sales-type table: private 58,229 (+4.1%, 38.1%); fleet 89,985 (+5.4%, 58.9%); business 4,516 (+24.5%, 3.0%).
- Cross-check: autocar.co.uk — Chinese brands’ combined share 21.3% incl MG (down from record 23.3% in Sept); MG leading Chinese brand (+85% YoY), Jaecoo 7 best-selling model (3,412), BYD No.10 brand (6,065).
- Cross-check: teslant.com — BEV 48,858 = 32.0% of market (2026 high), +32.7% YoY; Tesla 282 (-44.8% vs 511), 41st of 54 brands, first month of delivery quarter.
- Top models Oct: Jaecoo 7 (3,412), Ford Puma (3,369), VW Golf (2,642), Mini Countryman (2,480), Kia Sportage (2,438).
- MG counted as SAIC (Chinese). Chinese share shown with and without MG (21.6% incl / 16.5% excl).