Ferrari raised its 2026 full-year guidance on 3 November, after third-quarter results came in slightly ahead of Wall Street expectations.
Revenue guidance moved from EUR 7.6 billion to EUR 7.65 billion. Adjusted EBITDA guidance rose from EUR 2.97 billion to EUR 3 billion, adjusted earnings per share from at least EUR 9.68 to at least EUR 9.85, and industrial free cash flow from at least EUR 1.55 billion to as much as EUR 1.65 billion. It is the second consecutive quarter in which the company has lifted its outlook.
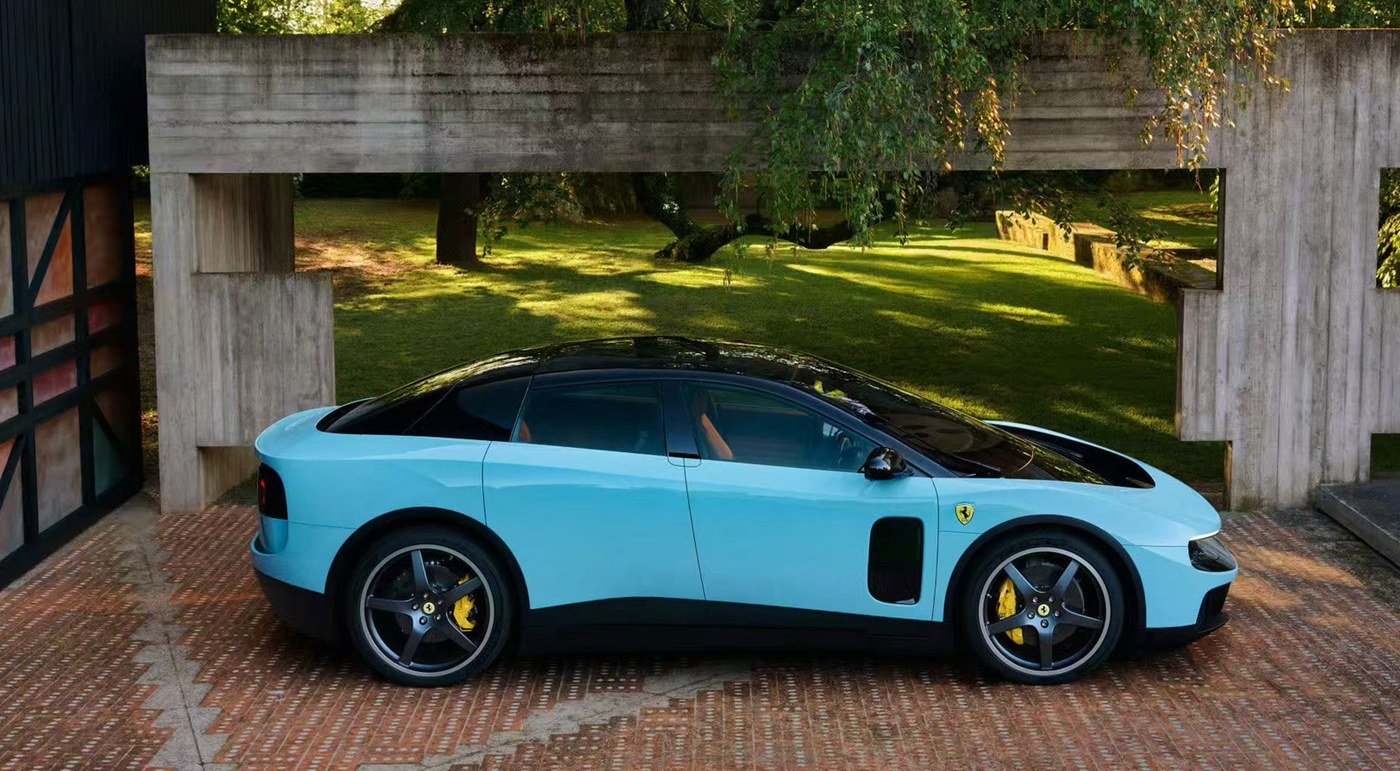
Fewer cars, richer specification
Deliveries in the first nine months came to 10,170 vehicles, 318 fewer than a year earlier. The company attributed the decline mainly to lower shipments to the Americas and to China, Hong Kong and Taiwan.
Ferrari said the improved outlook reflected stronger than expected demand for customer personalisation, lower than expected currency headwinds and a runner-up finish in the Formula One constructors’ championship.
Chief executive Benedetto Vigna said the order book already extends to 2028 and that two further models will be presented this year. The company continues to run branded events worldwide to deepen ties with customers and partners across racing, sports cars and lifestyle.
Analysts remain divided on how much of the beat is already priced in. Tom Narayan of RBC Capital Markets said results were broadly in line with expectations, and noted the share price could come under pressure because some investors had hoped for a larger increase in guidance.
The structure of the quarter is the point. Ferrari is defending profitability through mix and personalisation rather than volume, which insulates it from a soft Chinese market in a way mass manufacturers cannot replicate.
Editor’s note: This is an adapted translation of the original Gasgoo report. It has been trimmed and restructured for readability for an international business audience. The full original (in Chinese) is at https://auto.gasgoo.com/news/202611/4I70476840C109.shtml.