October sales reports arrived on 1 November. BYD sold 490,200 vehicles, up 11 per cent and its best month of the year. Leapmotor delivered 106,000, its fourth consecutive month above 100,000. Geely and Chery both beat last year, and XPeng and Xiaomi each crossed 50,000.
And yet the passenger car association had forecast October retail at about 1.6 million, some 650,000 fewer than a year earlier, a decline of 28.9 per cent.
Geely vice chairman Gui Shengyue described it plainly: the golden September and silver October basically disappeared this year for the first time, and may become normal.
The flat total, split in two
BYD, SAIC, Geely, Chery and Changan are China’s five largest groups by volume. Together they sold 1.760 million vehicles in October against 1.762 million a year earlier, a difference of under 2,000 units.
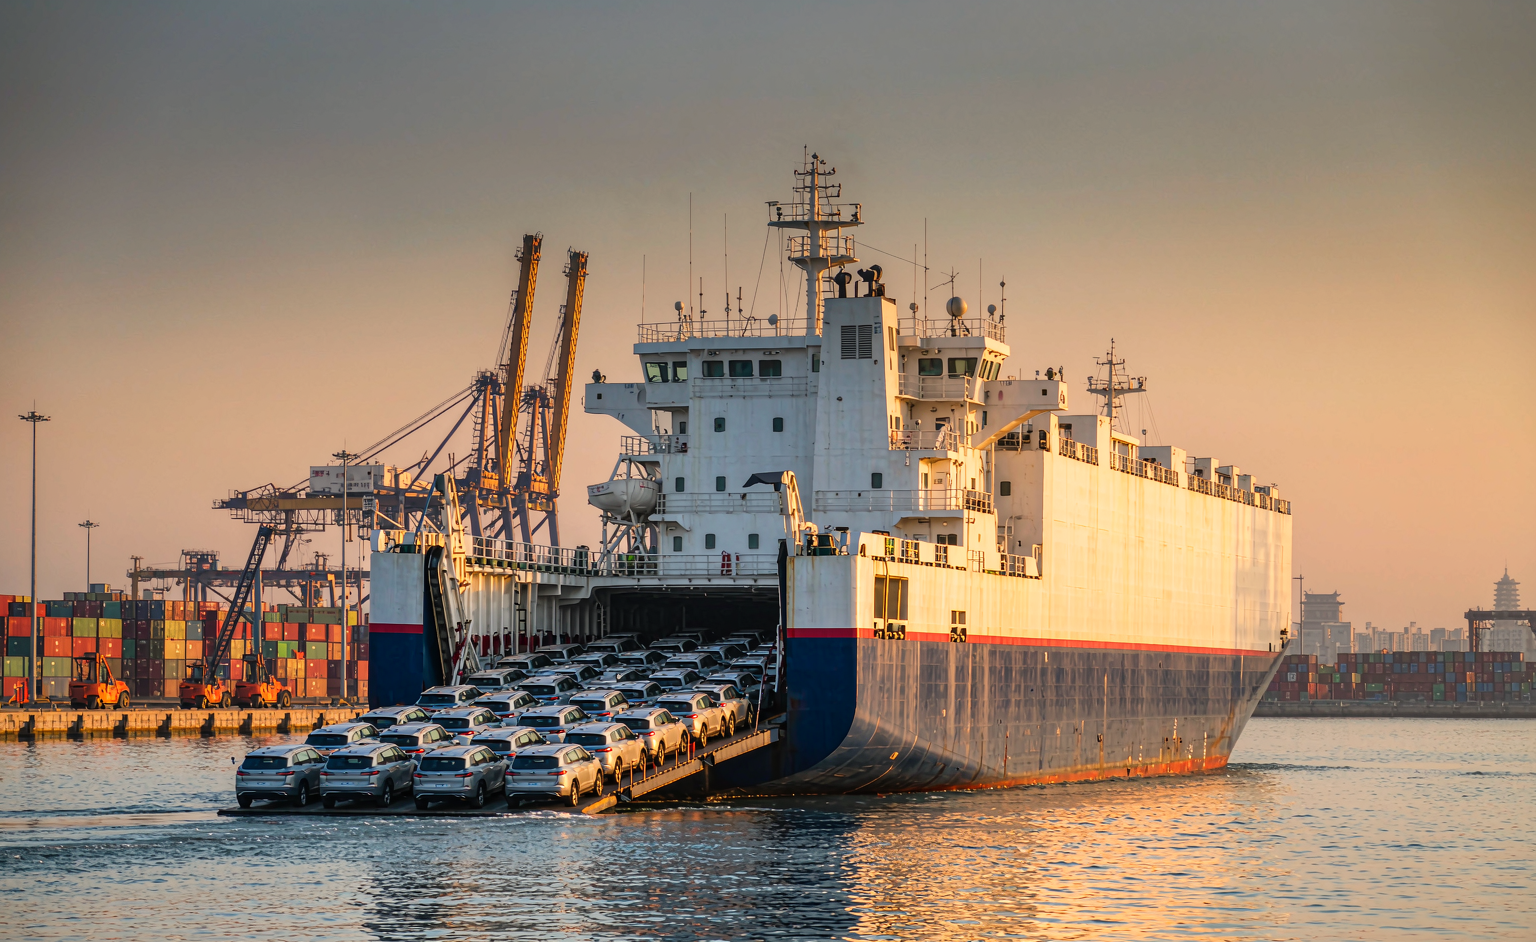
Split by destination and the accounts look nothing alike. Overseas sales reached 743,000, up 336,000 or 83 per cent. Domestic sales reached 1.018 million, down 338,000 or 25 per cent.
BYD had the smallest domestic decline, but its domestic volume has fallen every month this year. Its October overseas sales of 169,600 passenger cars and pickups had to cover a domestic shortfall of 38,000 before the remaining 48,000 became the 11 per cent growth in the headline.
SAIC and Changan did not cover theirs. SAIC sold 163,000 overseas, up 67 per cent, but lost 89,000 at home and finished 5.3 per cent lower overall. Changan sold 102,400 overseas, up 77 per cent year on year and 8.8 per cent sequentially, while domestic volume fell 40 per cent and total volume fell 44,000.
Chery Group sold 296,000 vehicles in October, of which 200,600 went overseas. Domestic wholesale was under 100,000, about 60 per cent of last year. Great Wall sold 120,000 with 62,900 overseas, leaving roughly 58,000 at home, less than the global volume of its Haval brand alone.
This is not a one-month effect
Changan sold 727,000 vehicles overseas in the first nine months, up 56 per cent, including more than 270,000 in the third quarter alone, and is targeting one million for the year. Its Brazil plant started production in March, and by October it had more than 350 sales and service outlets across 15 European countries.
Nationally, vehicle exports reached 8.205 million in the first nine months, up 66 per cent, while the domestic market contracted. The growth of the Chinese car industry is being relocated abroad in an accounting sense as well as a physical one.
The bottom of the price ladder broke first
Joint ventures have been losing share for years, and this year they lost it faster. SAIC-GM sold 25,865 vehicles in October, less than half last year and a third less than September. SAIC-Volkswagen sold 67,500, down 28 per cent. GAC-Toyota sold 53,000, down 25 per cent.
The new failure point is the cheapest segment, and it is a policy artefact. The 2025 trade-in subsidy was a flat RMB 20,000 for scrapping an old car and buying a new energy vehicle, whatever the price. From 2026 the subsidy is 12 per cent of the car price, capped at RMB 20,000, so a buyer needs a car priced around RMB 167,000 to collect the full amount.
The effect is regressive. A RMB 50,000 electric city car that received RMB 20,000 last year receives RMB 6,000 this year, a loss of RMB 14,000, close to 30 per cent of its price. A RMB 150,000 car loses RMB 2,000.
Petrol cars are being dragged by fuel prices. In September petrol retail fell 43 per cent and pure petrol 49 per cent, and the petrol share of retail dropped below one third for the first time. Conventional hybrids, which use less fuel, wholesaled 125,000 units in September, up 51 per cent, the fastest growth of any powertrain.
New platforms grow where old ones stall
At the price points where Wuling and Haval lost ground, another set of cars sold well. Leapmotor delivered 106,000 in October, up 51 per cent, with its two millionth vehicle due off the line in November. Geely Galaxy sold 153,000, up 20 per cent and 17.6 per cent above September. Changan Nevo sold 63,600, up more than 70 per cent.
Smaller brands grew too. Aion sold 42,400, up 57 per cent and higher for eight consecutive months, with the i60 reaching its 100,000th delivery and the Ray7 preselling at RMB 128,800 to RMB 158,800 with more than 6,800 orders in two hours. BAIC Arcfox sold 26,300, up 13 per cent, and 161,800 in the first ten months, up 46 per cent. NIO’s Firefly rose 31 per cent and Great Wall’s Ora doubled.
These brands sell at the same prices as Wuling and Haval and face the same subsidy and purchase tax rules, and they moved the other way. The difference is that most of their volume comes from models launched on new energy platforms in the past two or three years.
A large part of that growth also went abroad. Leapmotor exported more than 27,000 in September and started building the B10 at its Zaragoza plant in Spain in October. Geely exported 83,000 new energy vehicles in October, six times last year. GAC exported 197,700 in the first nine months, up 139 per cent, led by Aion. XPeng delivered 50,237 in October, a record, of which 13,326 went overseas, and the entire increase over last year came from exports.
Strip out exports and far fewer brands achieved net growth in China in October than the headlines suggest.
High base, high price
Harmony Intelligent Mobility delivered 33,537 in October, about half of last year. Much of that comes from the base: the new Aito M7 launched in September last year drove more than 110,000 firm orders in that month, and October delivered 68,216, its highest ever.
Base effects only explain part of it. Over the past year the brand’s on-sale line-up went from 10 models to 18, and average monthly deliveries per model fell from about 6,800 to about 1,900, barely a quarter of last year.
Editor’s note: This is an adapted translation of the original Gasgoo report. It has been trimmed and restructured for readability for an international business audience. The full original (in Chinese) is at https://auto.gasgoo.com/news/202611/3I70476727C108.shtml.