Keda Intelligent filed for a Hong Kong listing on 22 October with two claims to market leadership, one shrinking robot business and a chairman who sold RMB 250 million of stock before the paperwork went in.
The Hefei company, listed on Shenzhen’s ChiNext since 2011, is pursuing a dual A plus H listing. Its pitch rests on Frost and Sullivan rankings: first in China by cumulative industrial manipulator revenue from 2020 to 2025, and first in the lithium battery industry by cumulative stacker crane revenue.
The second curve is still a curve
Robots contributed RMB 1.024 billion of revenue in 2023. That fell to RMB 586 million in 2024 after the company divested loss-making subsidiaries in AGV and body-in-white welding, recovered to RMB 701 million in 2025, and reached RMB 373 million in the first half of 2026, or 24.02 per cent of group revenue. It has not returned to its 2023 level.
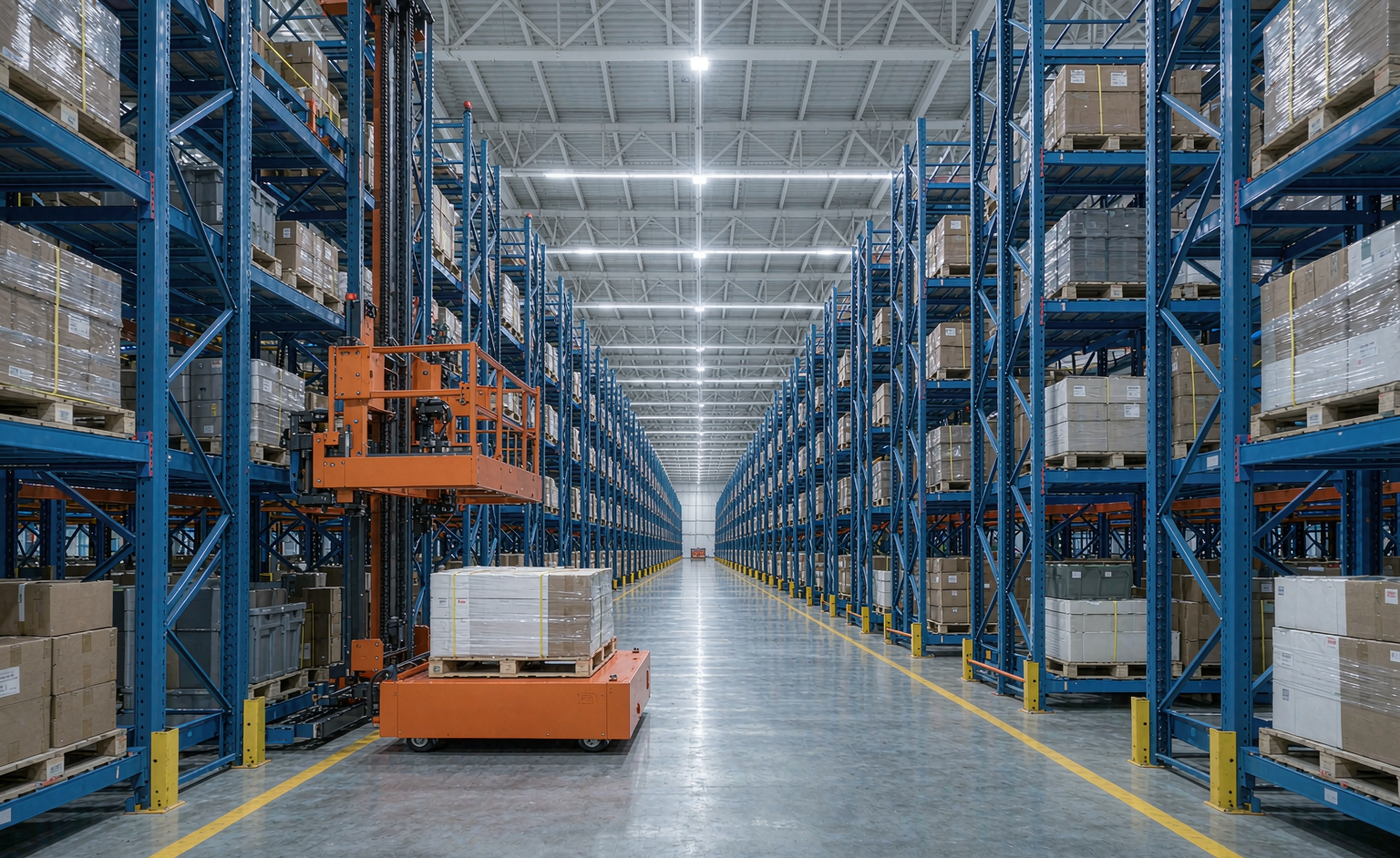
The three product lines have diverged. Manipulators are the only line with rising volume and price: first-half revenue of RMB 245 million, up 22.4 per cent, orders from 458 to 487, and average order value from RMB 437,000 to RMB 504,000 on lithium battery demand. Stacker cranes are buying volume with price, with orders up from 74 in 2023 to 100 in 2025 while average order value fell from RMB 2.811 million to RMB 1.757 million. Inspection robots are contracting, with first-half revenue down 45.9 per cent to RMB 33 million and orders down from 27 to 20.
Both leadership claims use cumulative revenue, and the stacker claim is narrowed to lithium battery customers rather than the whole market. Cumulative framing over six years can flatter a ranking that annual data would not support.
What the cash flow says
Group revenue was RMB 3.025 billion in 2023, RMB 2.687 billion in 2024 and RMB 3.015 billion in 2025, with net margin moving from negative 5.6 per cent to 2.8 per cent. Power equipment and storage, mostly State Grid tenders, is now 74 per cent of revenue, and the largest customer’s share rose from 23.5 per cent in 2023 to 34.5 per cent in the first half of 2026.
Operating cash flow is seasonal and worsening at the half year: negative RMB 104 million in the first half of 2025, negative RMB 159 million in the first half of 2026, because State Grid budgets and settlement cycles push collection into the fourth quarter. At the end of June the company held RMB 263 million of cash against RMB 1.757 billion of receivables and RMB 249 million of borrowings.
Internationalisation is a slide, not a segment
Overseas revenue was 2.2 per cent of the total in 2025 and 1.3 per cent in the first half of 2026, under RMB 20 million. The company bought 70 per cent of Zhejiang Yuanguang Electric for RMB 151 million in May 2026 specifically to acquire North American UL and European KEMA certifications. Its largest overseas contract, a framework agreement for the Al-Daura power plant in Baghdad, is worth about RMB 885 million and has recognised no revenue.
Governance is the part institutional investors will underwrite first. Huang Mingsong, chairman and founder since 2002, holds 21.84 per cent directly, sold 20.49 million shares for about RMB 250 million between August and October 2025, and has 63.65 million shares pledged. JD’s Suqian entity, which bought 5 per cent for RMB 618 million in 2017, remains the second largest holder at about 2.4 per cent. The board secretary resigned six days before the refiling, and in April 2024 regulators issued warning letters over a material deviation between 2023 guidance and the audited annual result.
A company can have real robot customers, a credible grid business and a listing story that still does not hold. Keda has the first two. The third is what Hong Kong will price.
Editor’s note: This is an adapted translation of the original OFweek report. It has been trimmed and restructured for readability for an international business audience. The full original (in Chinese) is at https://robot.ofweek.com/2026-11/ART-8321201-12003-30709966.html.